Chain Integrity
Supply chain transparency specification ISO 22095 governs the accounting boundaries for mass balance segregation of flax fibres moving from agrarian collection centers to industrial spinning mills in northern provinces. This operational rulebook establishes how spinning mills verify incoming raw material batches against stated origin claims without mixing certified lots with conventional crops during transit. Material accounting stops at the factory gate where roving frames begin mechanical drafting, so finished yarn lots rely on internal mill records rather than the standard for subsequent stages.
Mill auditors check incoming delivery notes against daily consumption logs to prevent inventory inflation within the storage warehouse. Batch segregation protocols demand strict physical separation or mathematical proportioning depending on the chosen chain of custody model selected by the mill management.
Mill Verification
Internal quality auditors inspect physical bales inside the receiving dock before signing warehouse transfer documents that release flax lots into the carding machinery. Incoming moisture content readings must match supplier certificates within tight percentage bands to prevent premature rotting during long term indoor storage. Weaving supervisors record yarn lot numbers on floor sheets before warp beams enter industrial looms for production runs.
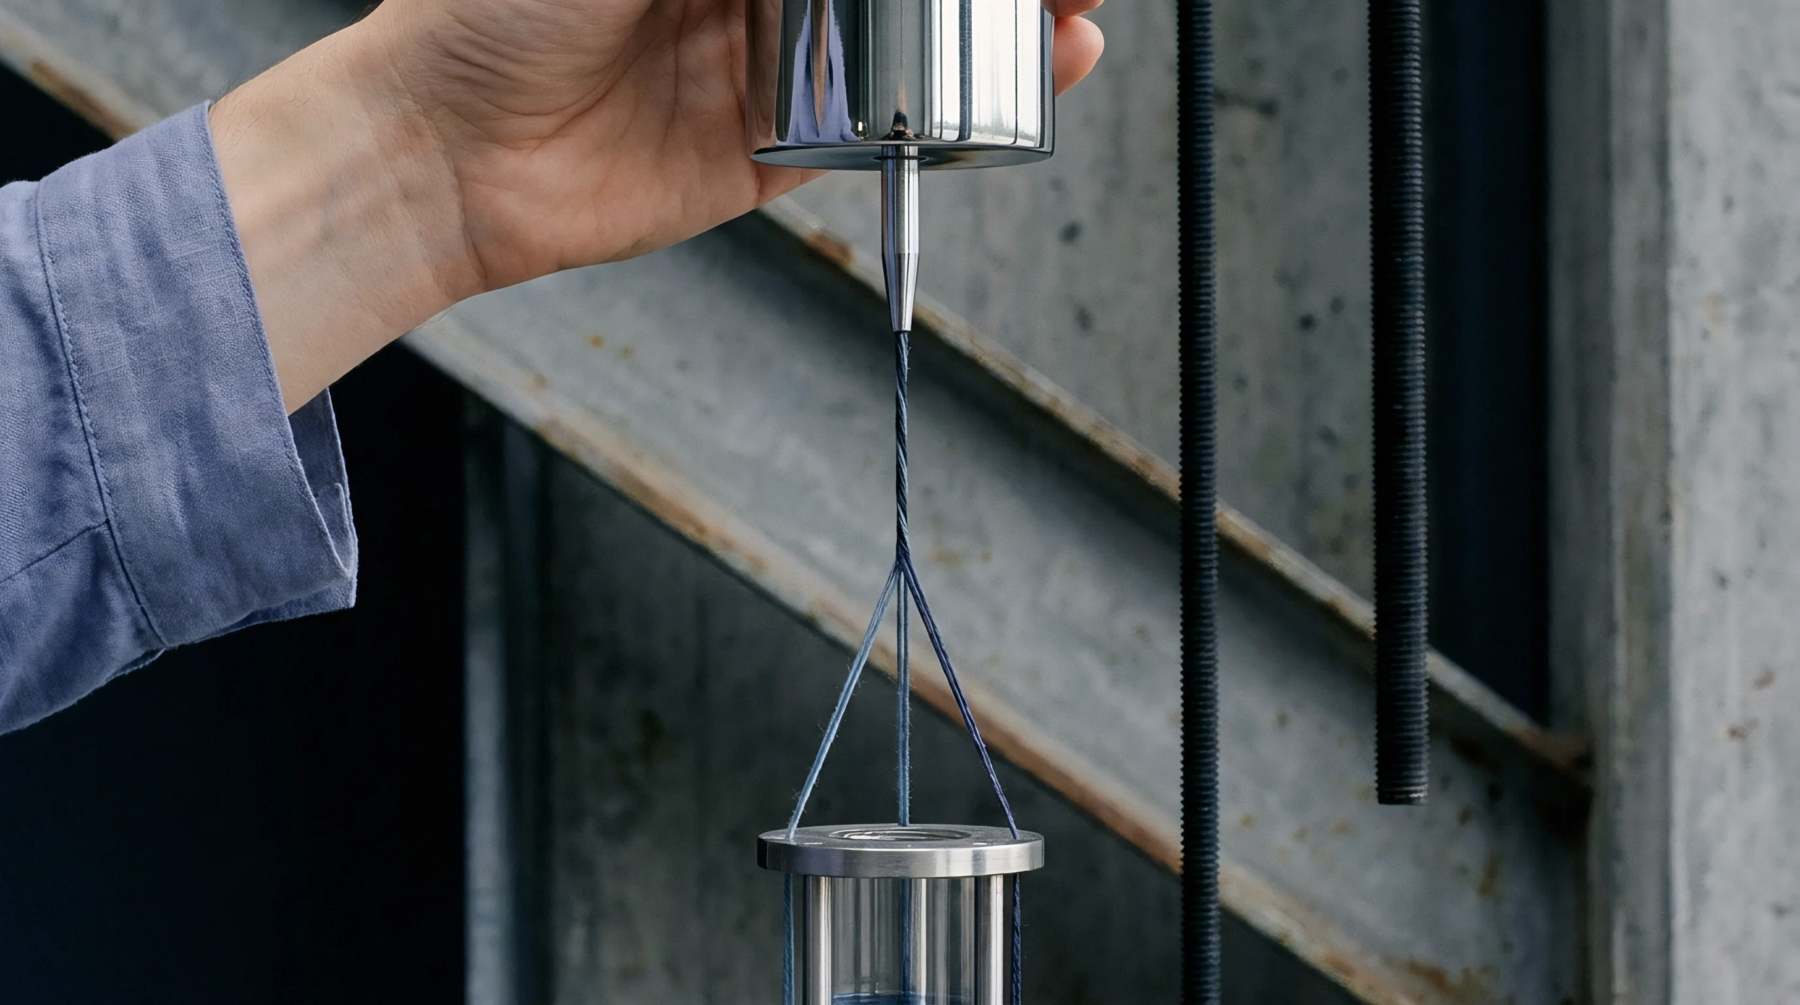
Fabric inspection desks examine finished linen cloth for breaking strength and thread density anomalies using standardized laboratory testing equipment. Laboratory technicians compare grey cloth tensile test results against buyer purchase orders to determine whether weaving mills meet contractual delivery thresholds.
Custody Documentation
Shipping supervisors compile monthly mass balance ledgers that reconcile total certified flax fibre inputs against finished linen export volumes leaving the finishing plant. Customs declarations list final fabric compositions based on laboratory assay sheets generated during the bleaching and dyeing procedures. Export documentation requires complete chain of custody records showing every custody transfer point from the initial retting tank to the final container loading bay.
Mill accountants review these reconciliation ledgers quarterly to verify that output claims match raw material input quantities recorded at the factory entrance. Accurate mass balance calculations protect export shipments from regulatory rejection at destination ports where customs authorities demand verifiable proof of material origin claims.